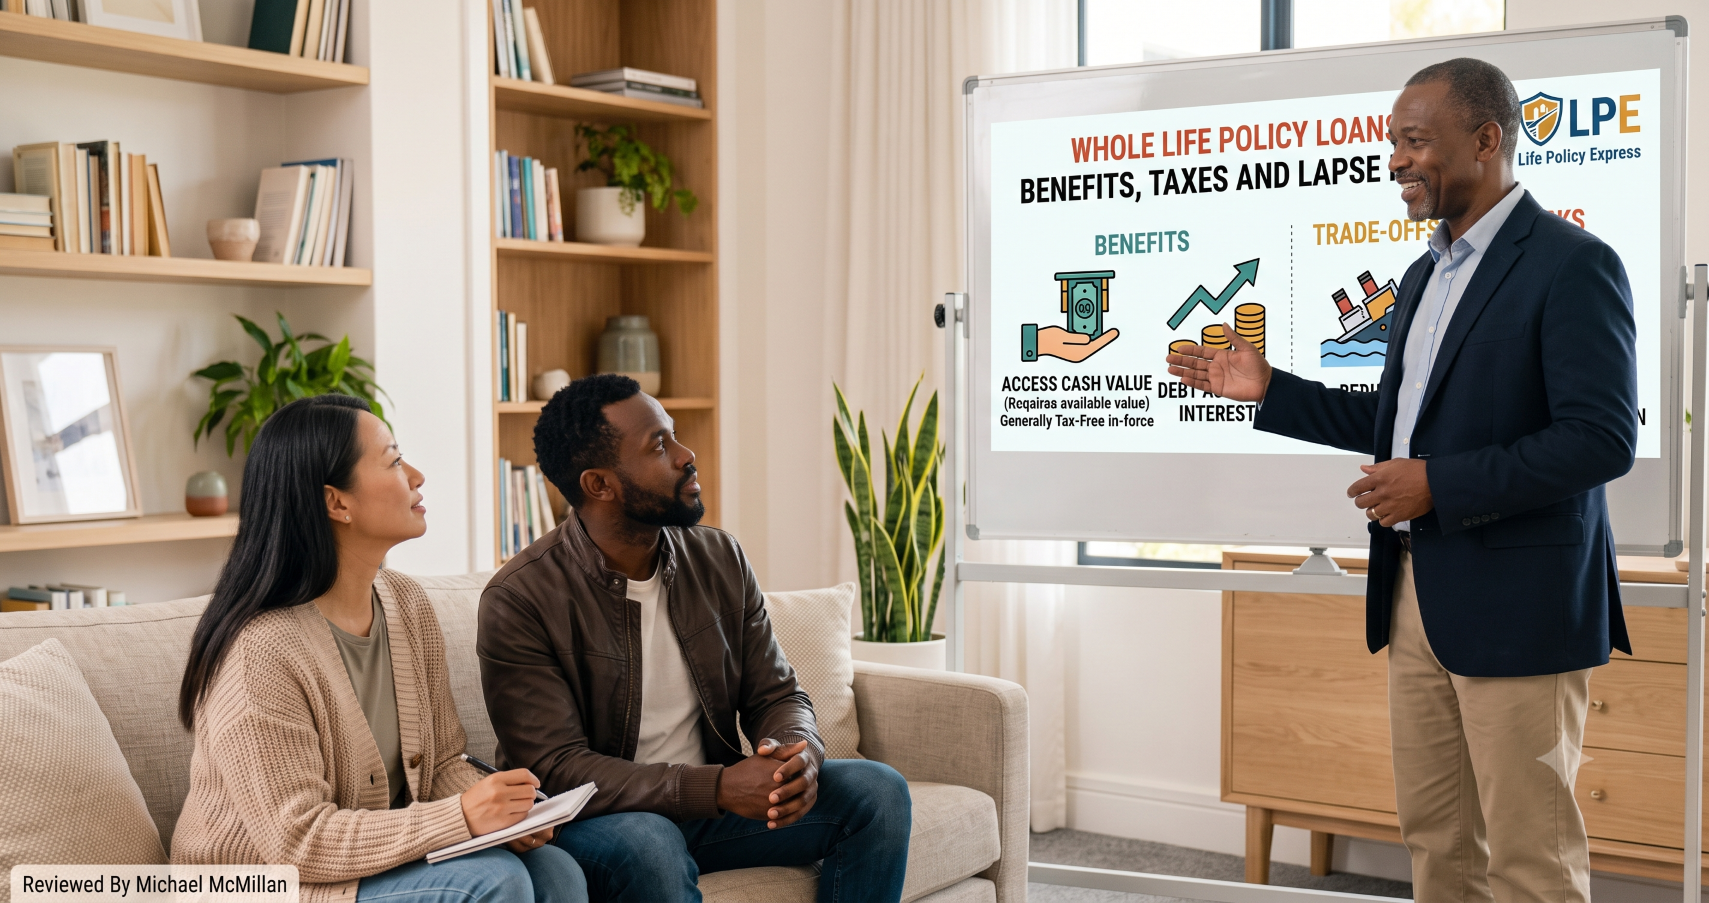
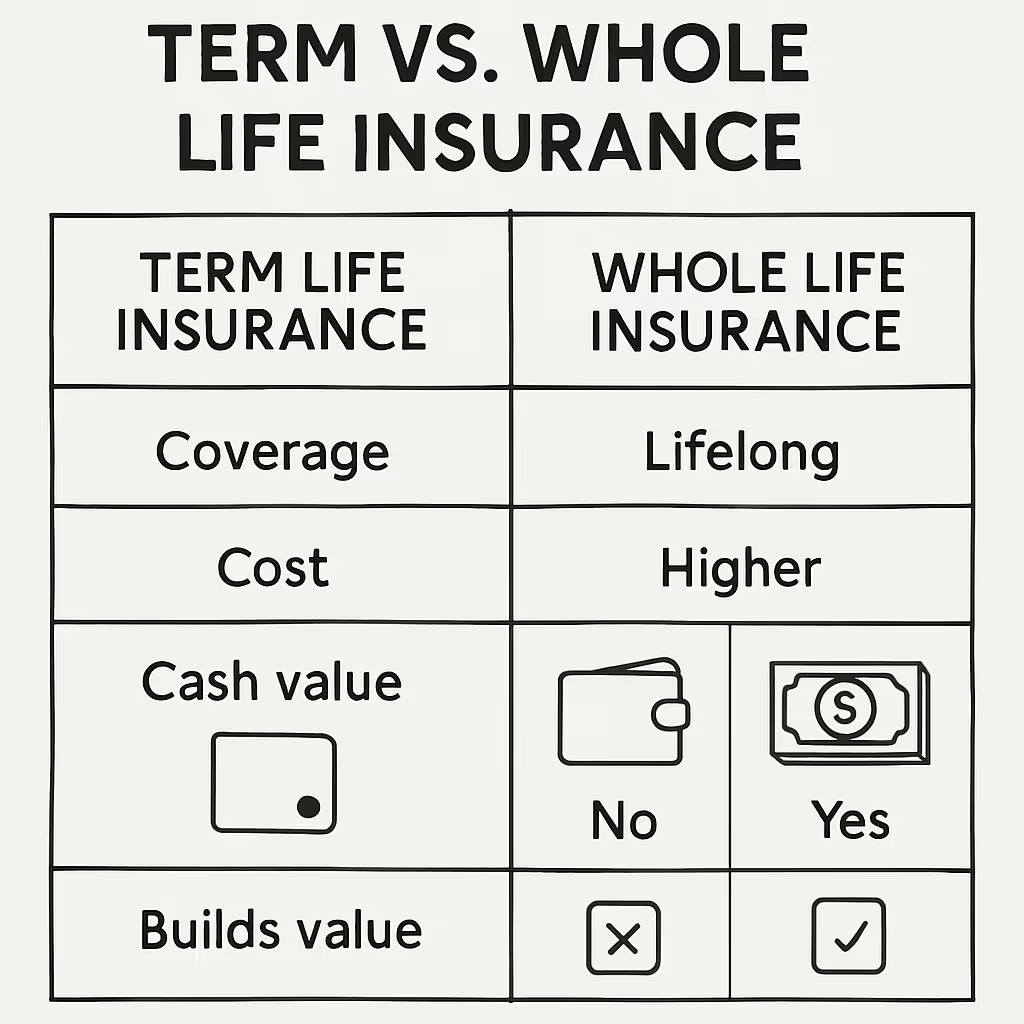
A whole life policy loan lets the owner borrow against available cash value without an external credit check. Interest accrues, and the loan balance reduces net cash value and the death benefit. An unmanaged loan can contribute to policy lapse and possible taxable income, so monitor in-force values and consult qualified insurance and tax professionals.
Understand whole life policy loans, including interest, death-benefit reductions, dividend treatment, lapse risk, MEC rules, and potential taxes.
A whole life policy loan lets the policy owner borrow against available cash value under the contract. The insurer lends the money and uses the policy value as collateral. The loan does not remove the obligation to maintain the policy, and interest begins accruing according to the loan terms.
No. A withdrawal permanently removes value from the policy and may reduce the death benefit. A policy loan creates a debt secured by the policy. The loan balance, including accrued interest, generally reduces the cash value and death benefit available to support the contract.
Policy loans generally rely on available policy value rather than the owner’s credit history. The amount available, interest method, and other terms are governed by the contract. A loan is not available until sufficient value exists.
Interest accrues on the outstanding balance. Policies may use fixed or variable loan rates, and interest may be charged in advance or in arrears. Ask how unpaid interest is handled. If interest is added to the balance, the debt can compound over time.
Some whole life policies treat the portion securing a loan differently when calculating dividends. This is sometimes described as direct recognition. Other policies may not directly change the dividend treatment of borrowed value. Dividends are not guaranteed under either approach, and the contract and current dividend scale control actual results.
Contractual cash value may continue to develop according to the policy schedule, but that does not make a loan free. The outstanding balance and interest reduce net policy value. Dividend treatment may also differ. Evaluate the policy on a net basis: cash value and death benefit after subtracting the loan.
If the insured dies while a loan is outstanding, the insurer generally subtracts the loan balance and accrued interest from the death benefit. Beneficiaries receive the remaining amount, subject to the policy terms.
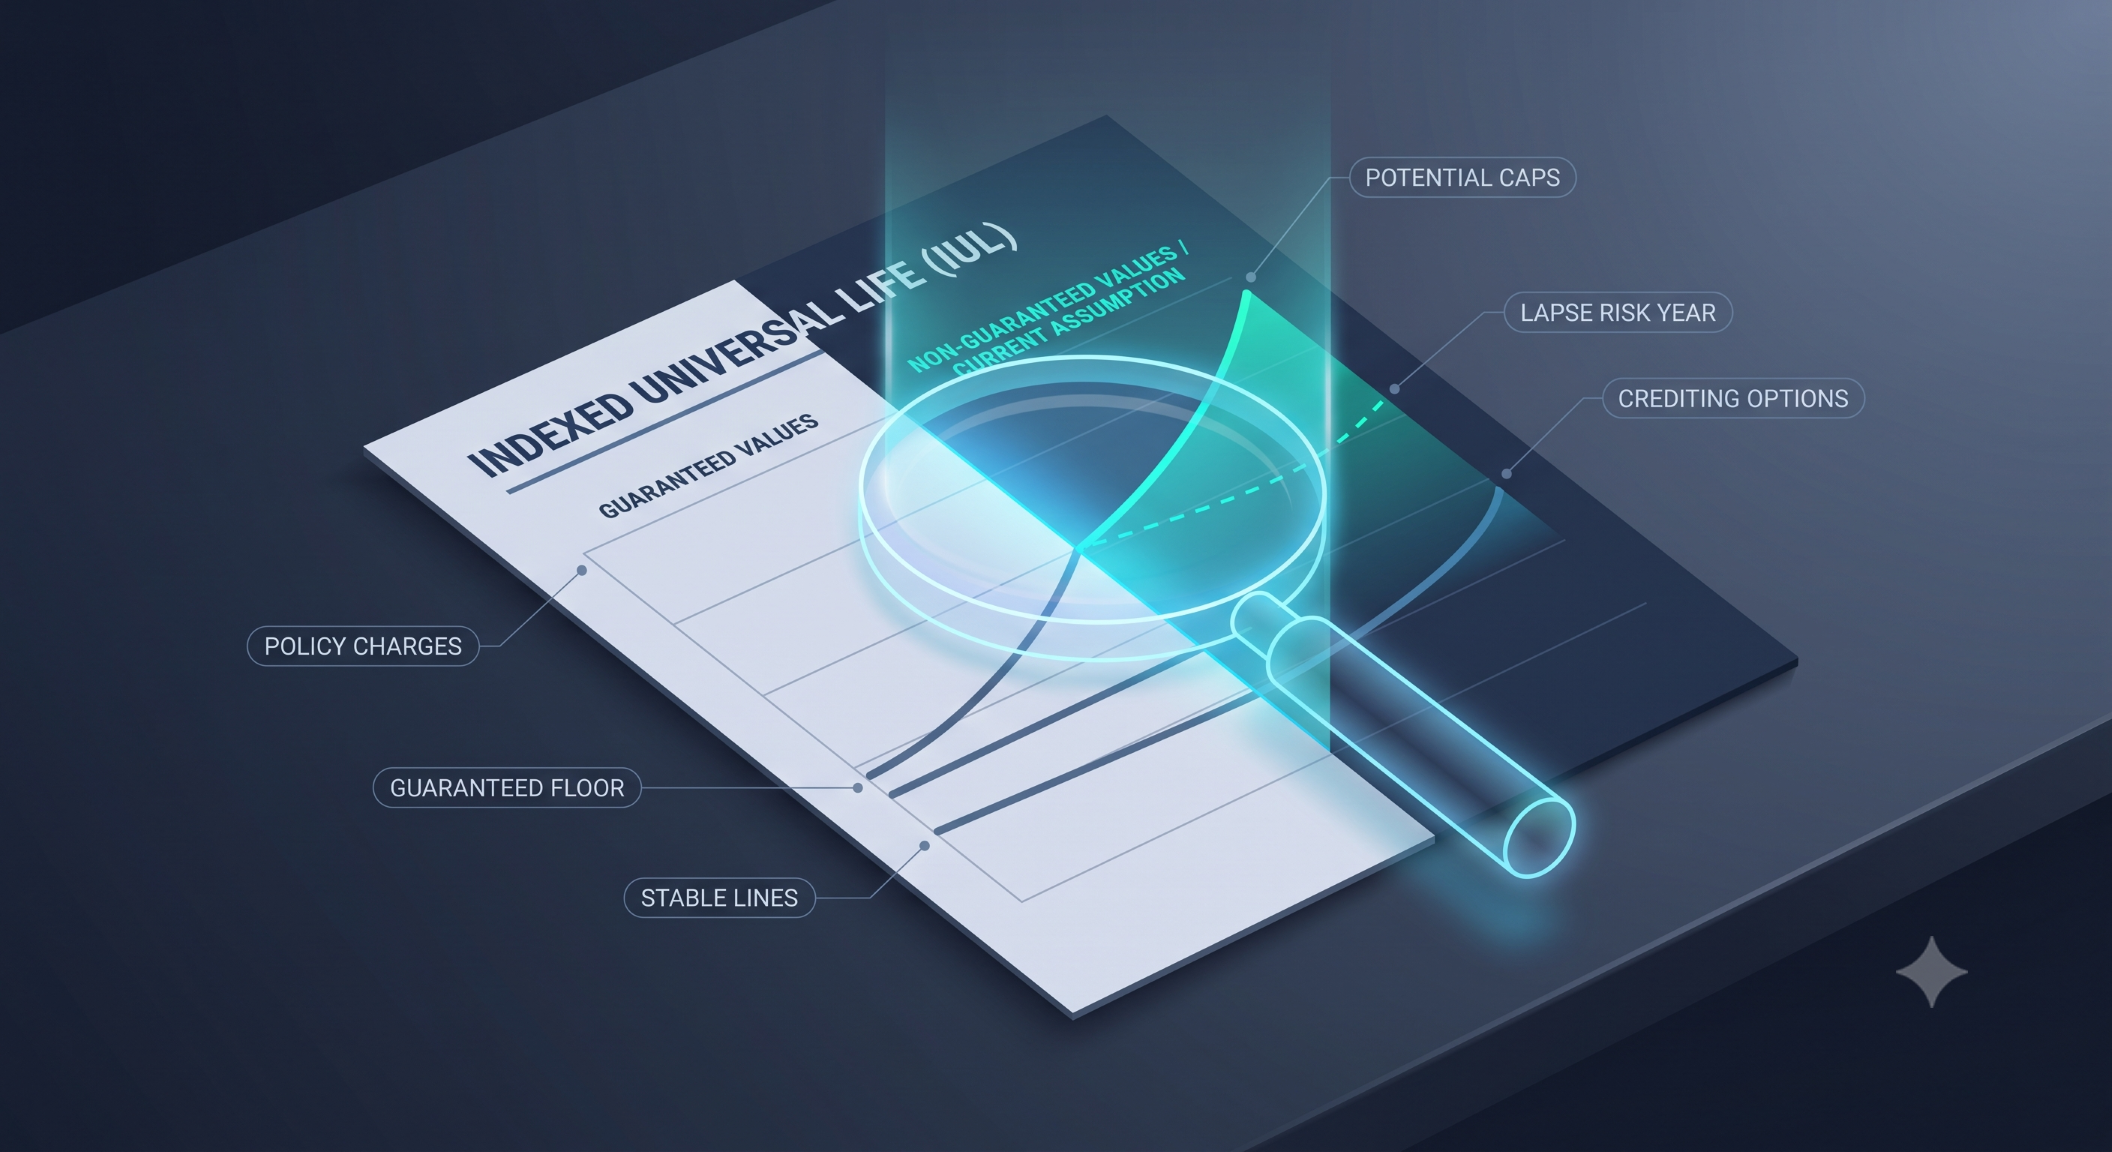
Yes. A growing loan balance can consume the value supporting the policy. If the remaining value becomes insufficient and additional premium is not paid, the policy may lapse. A lapse ends coverage and can also create a tax problem when the policy has gain.
Calling policy loans “tax-free” without qualifications is misleading. A loan is generally not treated as income when it is taken from a life insurance contract that remains in force, but tax treatment can change if the contract is a modified endowment contract, is surrendered, or lapses. Gain can become taxable, and an outstanding loan may affect the calculation.
Tax rules are individual and can change. Consult a qualified tax professional before using policy loans as an income strategy.
A policy that receives too much premium relative to its death benefit can become a modified endowment contract, commonly called a MEC. Distributions from a MEC generally receive less favorable tax treatment, and loans may be treated as distributions. Ask whether planned funding could cause MEC status and how the insurer monitors the limit.
Review the annual statement and request an in-force illustration showing the current loan. Compare a scenario that pays loan interest with one that allows interest to accumulate. Revisit the strategy after changes in dividends, premiums, health, retirement income, or estate goals.
Policy loans are sometimes presented as a source of retirement income. The strategy depends on maintaining enough value to support both the death benefit and the loan. Ask for conservative scenarios, including lower dividends, earlier withdrawals, longer life expectancy, and higher loan interest.
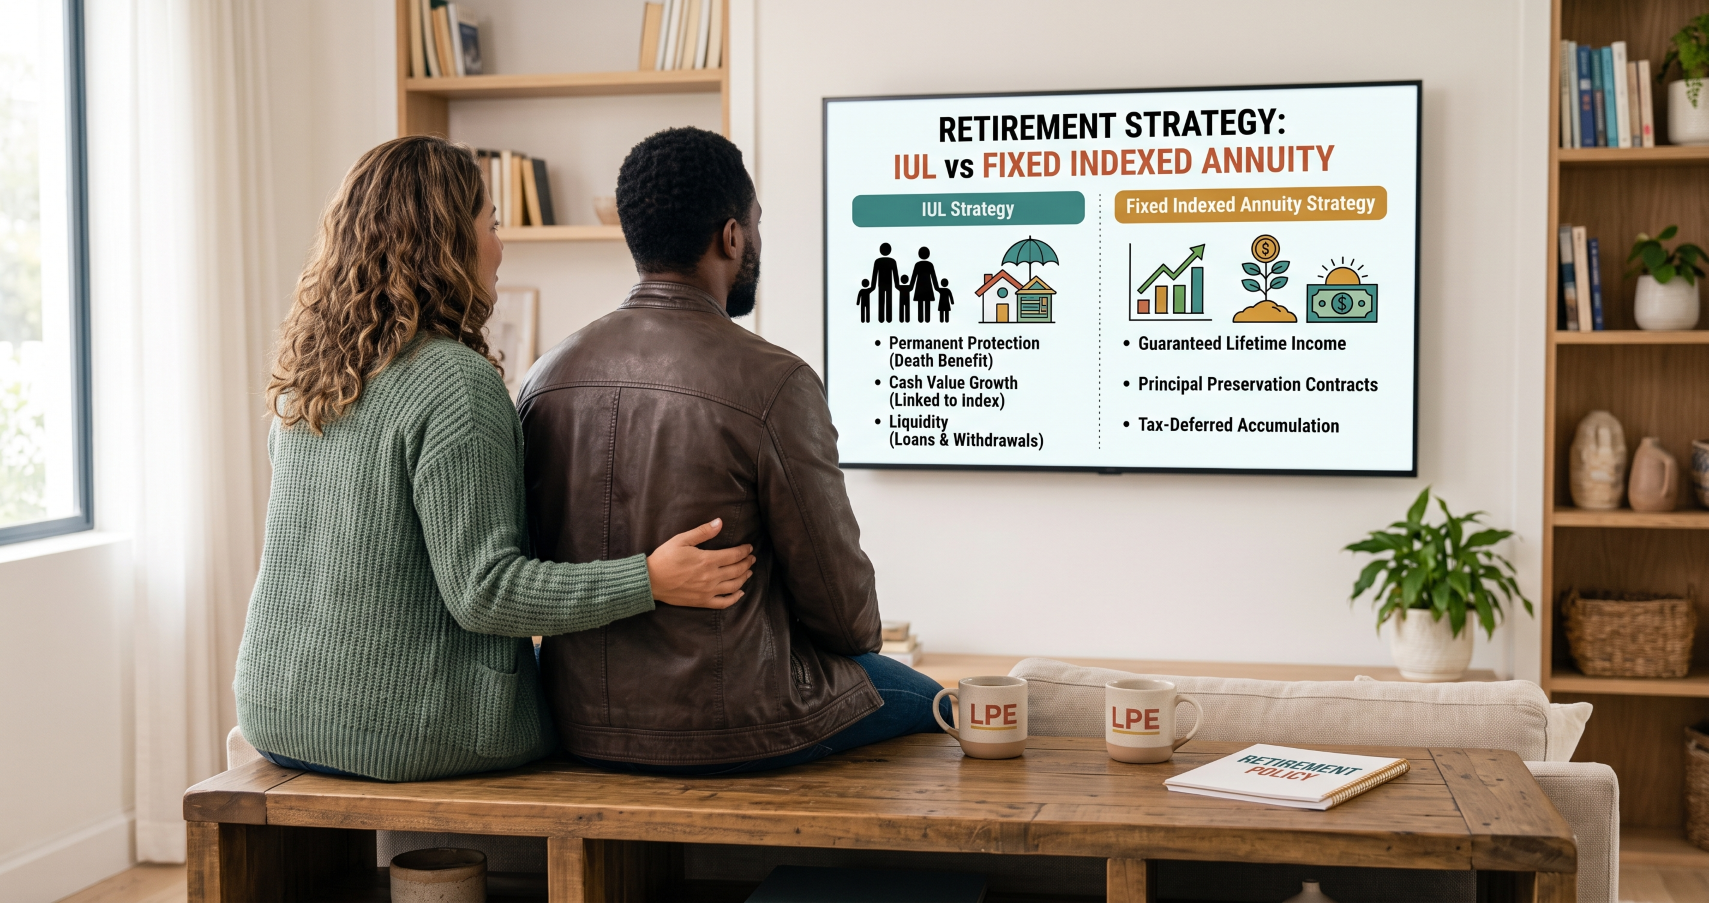
If the primary objective is guaranteed lifetime income, compare the strategy with appropriate annuity and retirement-account options rather than assuming life insurance is the only solution.
A whole life policy loan can provide access to value without an external lender, but it is still a loan. Interest accrues, benefits are reduced, and an unmanaged balance can contribute to lapse and potential taxation. Use current in-force values and qualified insurance and tax guidance before borrowing.
For a broader look at guarantees, cash value, and tradeoffs, read our whole life insurance guide.